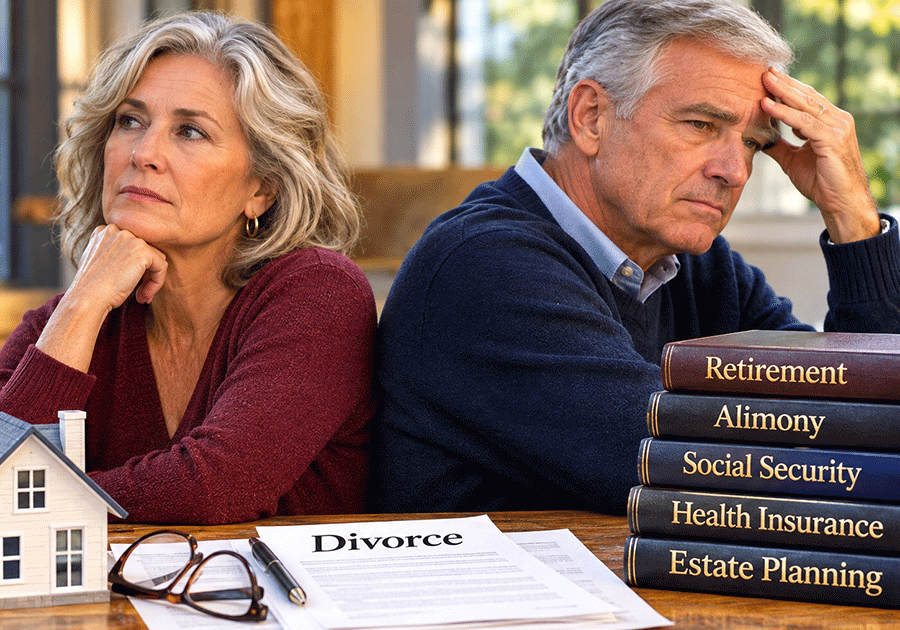
Divorce later in life, commonly called gray divorce, presents legal and financial challenges that differ from those faced by younger couples.
People divorcing in their 50s, 60s, or older may have spent decades accumulating retirement savings, building home equity, and planning for retirement together. Divorce requires them to divide those resources, often when they have limited opportunities to replace them.
In Massachusetts, several issues deserve particular attention.
Dividing Retirement Accounts and Pensions
Retirement benefits are often among the most valuable assets in a long marriage.
Under Massachusetts General Laws Chapter 208, Section 34, retirement accounts and pensions may be divided as part of the marital estate.
Massachusetts follows equitable distribution, meaning that property must be divided fairly, although not necessarily equally.
Dividing retirement benefits can be complicated. Traditional retirement accounts generally contain money that will be taxed when withdrawn, while qualified Roth distributions may be tax-free. Pensions may require actuarial valuations, and certain retirement plans require special court orders to divide benefits.
The objective is not simply to divide account balances, but to consider the retirement income available to each spouse.
Alimony and Retirement
Alimony can be particularly important when one spouse earned substantially more than the other during a lengthy marriage.
Under Massachusetts law, general term alimony ordinarily terminates when the paying spouse reaches full retirement age under Social Security, although statutory exceptions exist.
For a couple divorcing in their mid-60s, this may mean that alimony will continue for only a limited period.
A spouse who has been financially dependent throughout a long marriage cannot assume that alimony will continue for life.
Consequently, alimony and the division of retirement assets must be considered together.
Social Security Benefits
Social Security retirement benefits are not divided as marital property in a Massachusetts divorce.
However, federal law may allow a divorced spouse to receive retirement benefits based on a former spouse’s earnings record if the marriage lasted at least 10 years and other eligibility requirements are satisfied.
A divorced spouse may qualify for benefits of up to 50% of the former spouse’s full retirement benefit. Different rules apply to survivor benefits.
These benefits generally do not reduce the former spouse’s own Social Security payments.
For couples approaching their tenth wedding anniversary, the timing of a divorce may have significant financial consequences.
The Marital Home
The marital home may represent a substantial portion of the couple’s wealth.
After decades of marriage, one spouse may want to remain in the house. However, maintaining it on a single income may be difficult.
Property taxes, insurance, repairs, and maintenance can consume retirement resources.
Selling the house may also produce capital gains tax consequences.
The parties must decide whether one spouse can realistically afford to retain the property or whether selling it and dividing the proceeds would better serve their financial needs.
Health Insurance and Medical Expenses
Health insurance becomes particularly important when divorce occurs before Medicare eligibility at age 65.
A spouse who depends on the other spouse’s employer-sponsored coverage may need replacement insurance following the divorce.
Even after Medicare eligibility begins, premiums, supplemental coverage, prescription expenses, and long-term care costs remain concerns.
Massachusetts courts may consider the parties’ ages and health when dividing marital property.
Estate Planning After Divorce
Older couples frequently have wills, trusts, life insurance policies, and retirement accounts naming one another as beneficiaries.
Massachusetts law generally revokes certain provisions benefiting a former spouse upon divorce, but exceptions exist, and federal law may govern some benefits.
Divorcing spouses should review their wills, trusts, beneficiary designations, powers of attorney, and health care proxies.
A divorce judgment may also require a spouse to maintain life insurance or other benefits for a former spouse.
The Financial Challenge of Starting Over
Perhaps the greatest challenge of gray divorce is that older spouses have fewer working years available to recover financially.
A marital estate that once supported one household must now support two.
Each spouse may need separate housing, transportation, insurance, and other living expenses.
A division that appears equal on paper may produce unequal financial results because of taxes, liquidity, and the income generated by different assets.
Massachusetts law recognizes these concerns by requiring courts to consider factors such as the parties’ ages, health, income, assets, and opportunities to acquire future income and property.
For couples divorcing later in life, a fair settlement must account not only for the value of their assets today, but also for their ability to support themselves throughout retirement.
Gray divorce ends a marriage, but its financial consequences may last for the remainder of both spouses’ lives.