Many trusts are administered by family members or other people who are not professional trustees. The recordkeeping and disclosure requirements can feel overwhelming, especially for someone who has never managed trust assets before.
A recent Massachusetts Appeals Court decision illustrates why these duties matter. In In the Matter of the Katharine M. Walker Irrevocable Trust (1998), the court affirmed a trustee’s removal after the trial judge found, among other things, that transactions involving trust assets were poorly documented. The Appeals Court explained that trustees must maintain contemporaneous, accurate records and that a failure to do so may be construed against the trustee.
What Massachusetts law requires
A trustee must keep adequate records of trust administration and keep trust property separate from the trustee’s own property. G.L. c. 203E, § 810. A trustee must also keep qualified beneficiaries reasonably informed about trust administration, respond to reasonable requests for information, and provide required accounts showing items such as trust assets, receipts, disbursements, liabilities, and trustee compensation. G.L. c. 203E, § 813.
These are legal obligations, but a few practical habits can make them easier to manage:
- Keep trust money in separate accounts. Title the accounts in the trust’s name and use the trust’s taxpayer identification number where required. The correct number depends on the trust’s tax status; some grantor trusts use the grantor’s Social Security number under IRS reporting rules.
- Use accounting software. Programs such as Quicken or QuickBooks can help track income and expenses, maintain a transaction history, and write checks from the trust account.
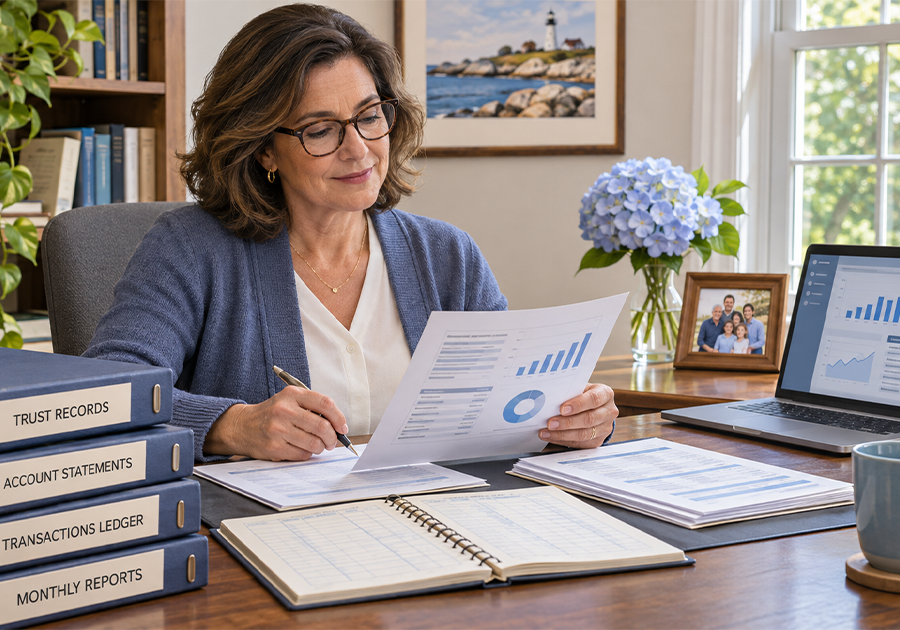
- Enter each transaction when you make it. Record the date, amount, payee or source, purpose, and category when you write a check, make a transfer, or receive money. Avoid relying on memory or reconstructing the records later.
- Reconcile the account statements promptly. Compare the software records with each bank statement as soon as practical after it arrives. This helps identify missing transactions or errors while they are still easy to investigate.
- Send monthly reports after reconciliation. Once the accounts are reconciled, provide beneficiaries with a report from the accounting program showing the month’s activity and current balances. Monthly reporting is a practical way to keep beneficiaries informed; the statute’s specific account requirements still apply.
- Have an accountant handle tax filings. Trust tax returns and related reporting can be complicated. An accountant can prepare the required filings and help the trustee use the correct taxpayer identification number and reporting method.
Good records make it easier for a trustee to explain how trust property was managed and to answer beneficiaries’ questions. In Walker, the court emphasized that the trustee—not the beneficiaries—had the responsibility to maintain reliable records as the transactions occurred.